Our archives on Philippines
Datafiles May 26

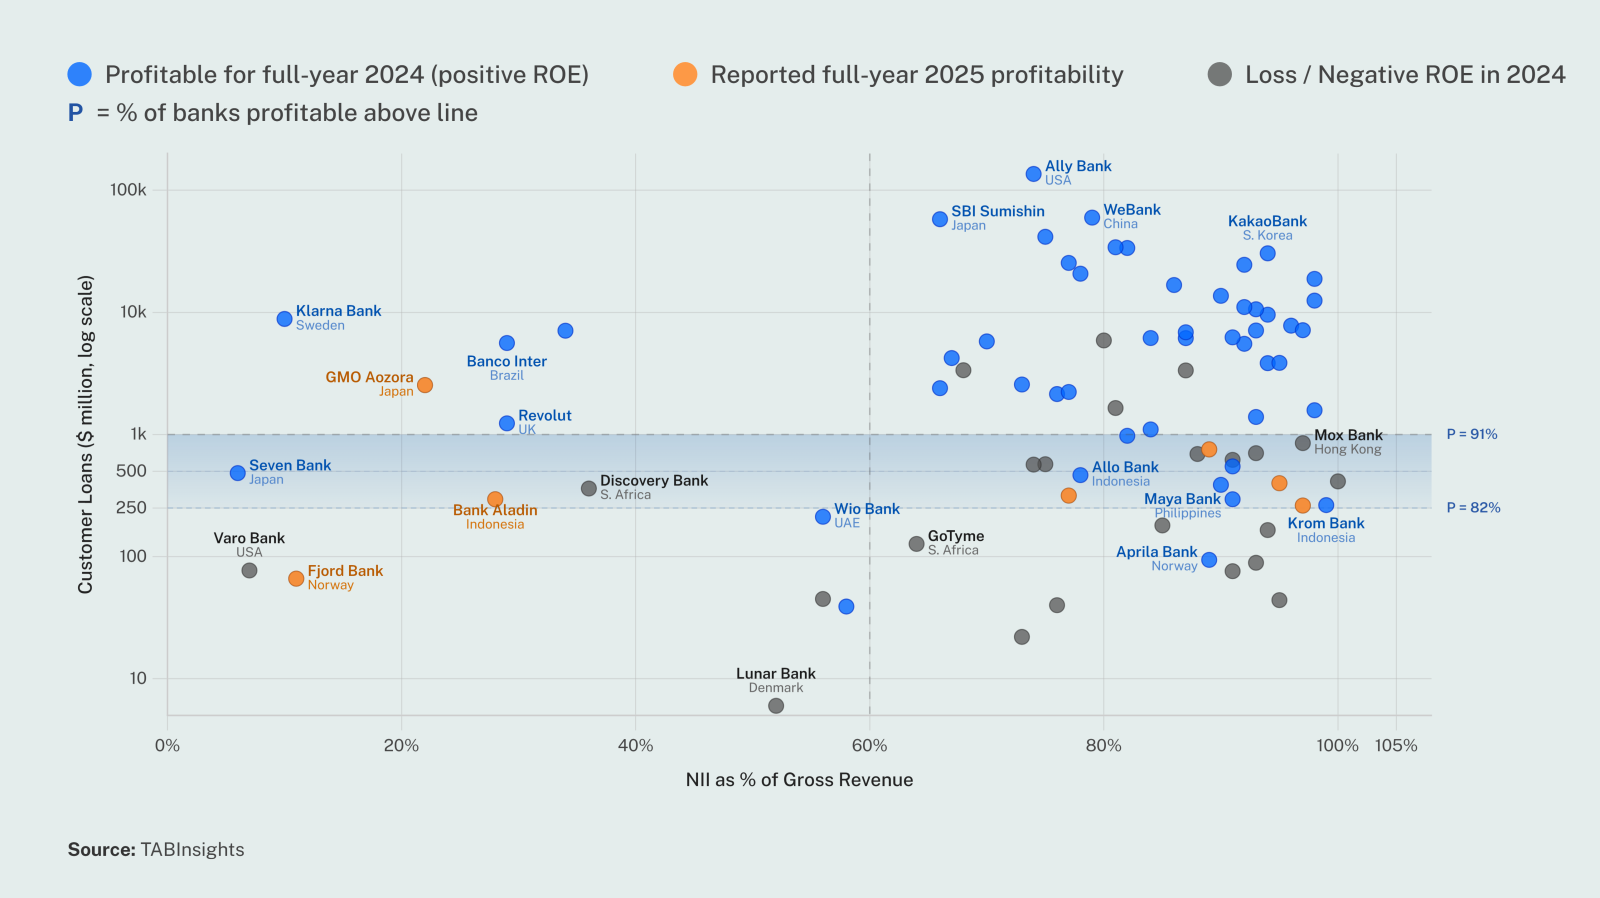
Digital banks with loan balances above $250 million are significantly more likely to be profitable, as scale and product diversification strengthen revenue. Most reach breakeven within three to six years. For those still unprofitable past the seven-year mark, N26 in Germany, Varo Bank in the US, Lunar Bank in Denmark and CIMB Bank Philippines among them, face an increasingly difficult case for continued investment.

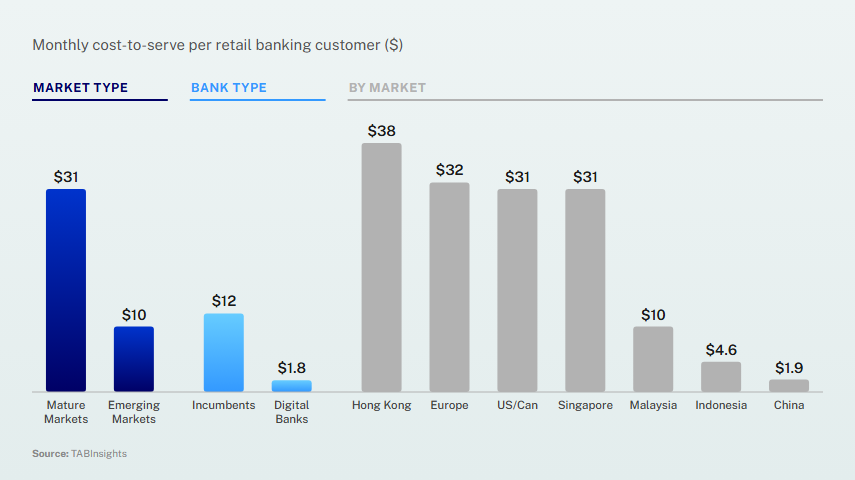
Digital banks serve customers far more cheaply than incumbents, but most generate less revenue for every dollar spent on servicing. Nubank and WeBank stand out, generating 4.1x and 3.8x their servicing cost in revenue respectively, outperforming leading incumbents. Most other digital banks fall short of incumbent benchmarks, showing that lower cost-to-serve alone does not guarantee stronger economics.

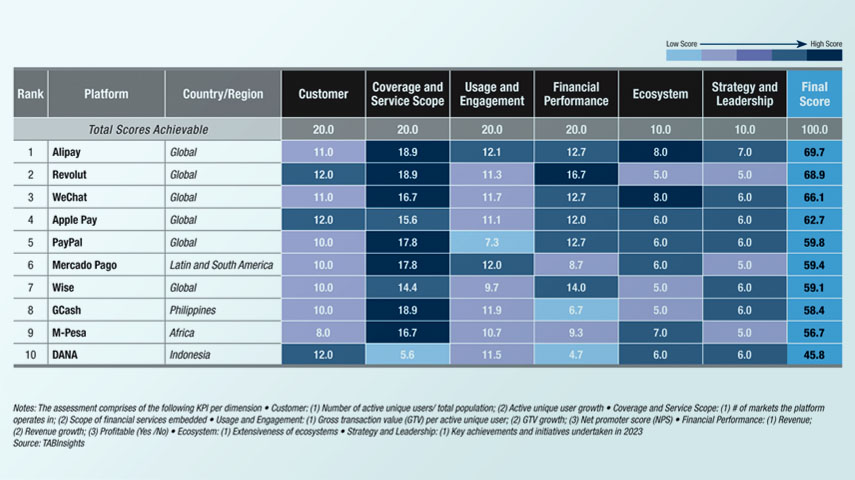
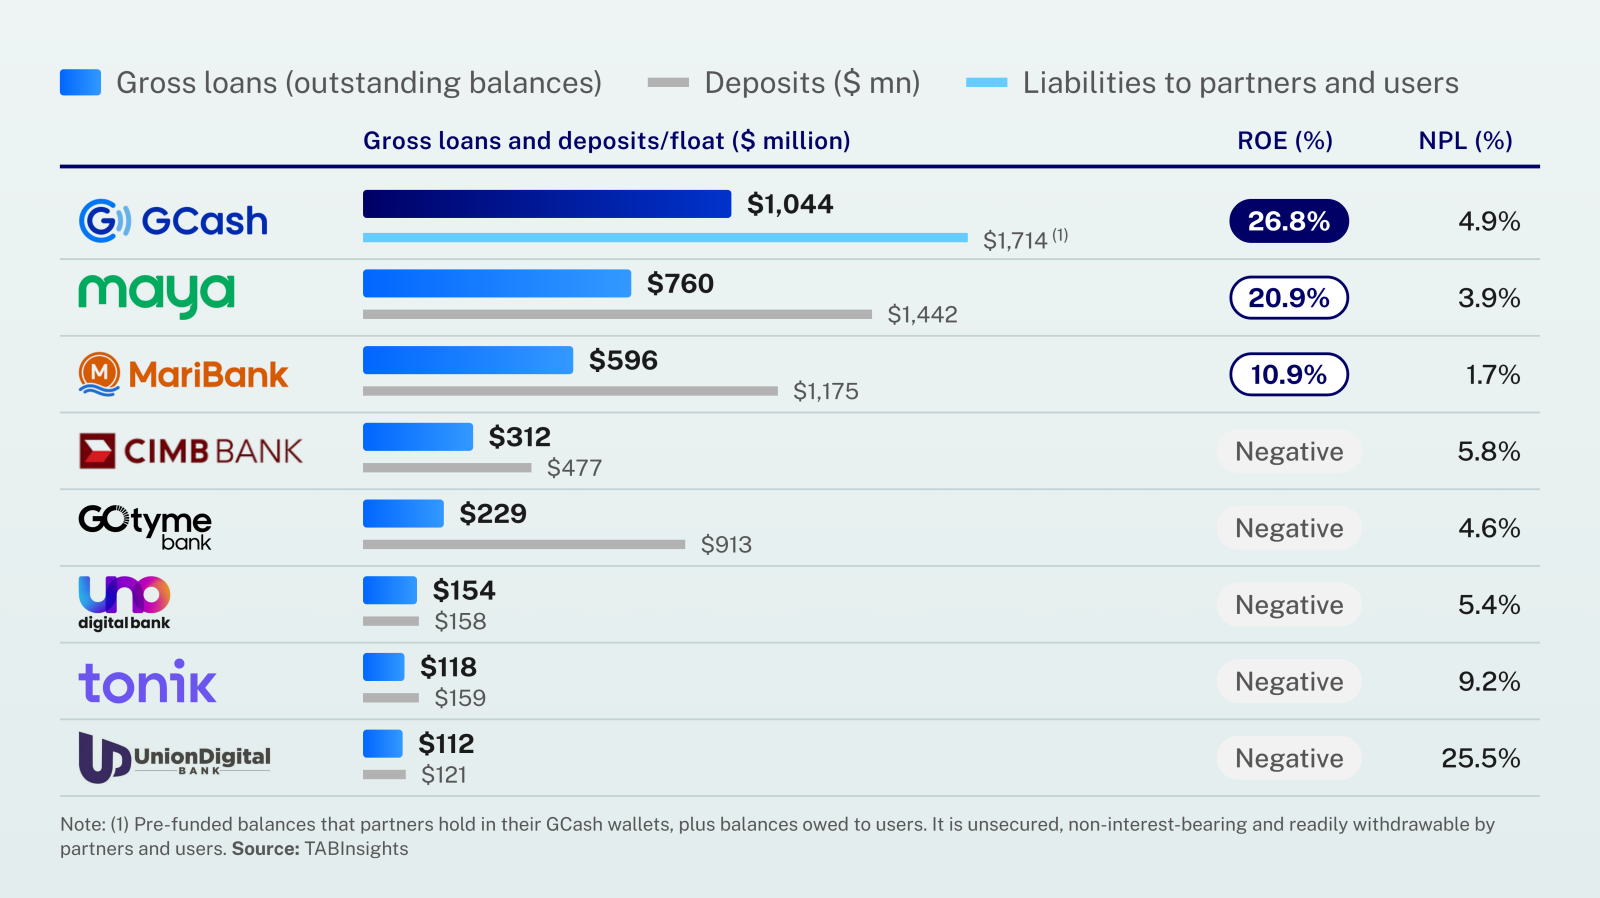
GCash has evolved from a payments platform into a bank-like lender, with a loan book and profitability exceeding those of the Philippines’ licensed digital banks. Lending now drives growth, but rising credit losses pose a growing challenge to profitability. Without a bank’s deposit base or banking regulatory framework, GCash’s model combines competitive advantages with structural risks.

Exclusive benefits are on your way. Subscribe and enjoy the benefits.